
Audit and accounting for construction and contracting companies in Qatar
Thiqa Consulting provides audit, tax and accounting for construction and contracting companies in Qatar: the yearly audit, contract-by-contract accounts, the corporate income tax return and withholding tax on foreign subcontractors. We agree the scope, responsibilities and fee before work starts. Tell us about your projects and we suggest where to start.
- Project by projectCosts and revenue tracked per contract
- Fixed feeAgreed in writing before we start
- Tender-ready accountsAudited figures when a client asks
- Clear guidanceWhat applies to you, and why
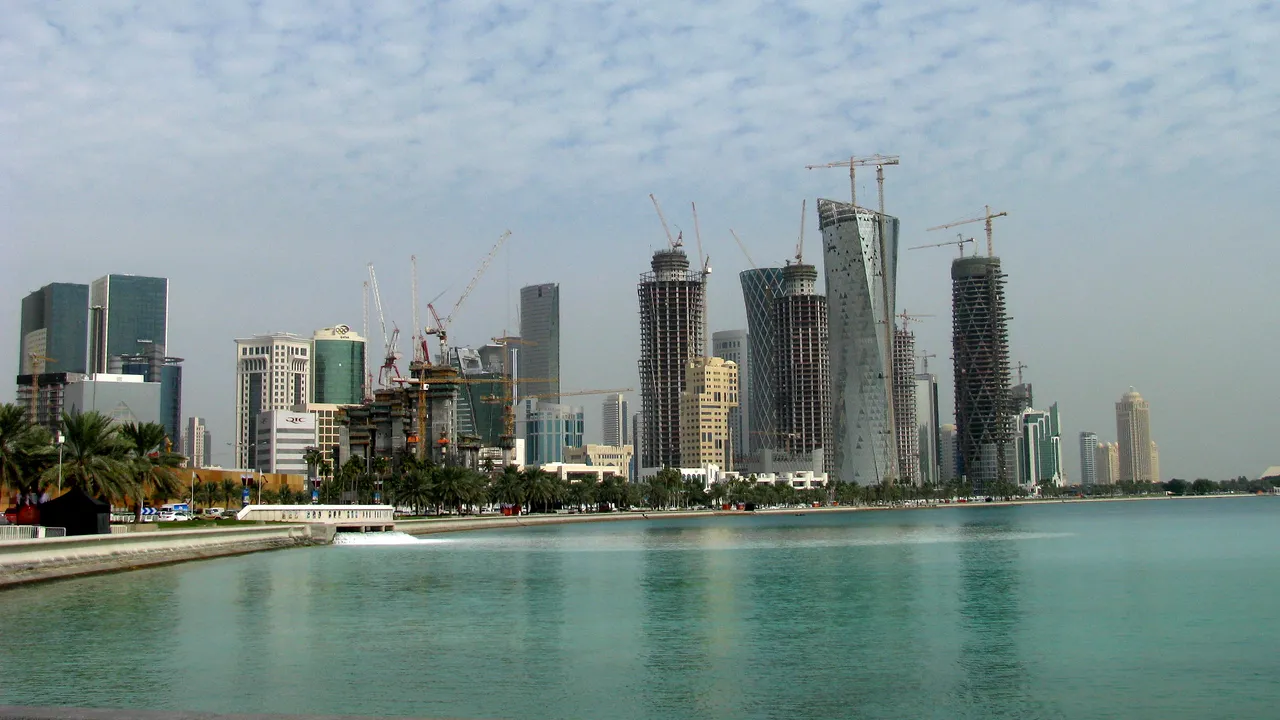
Tower cranes over buildings under construction in central Doha
What construction and contracting companies usually deal with
Contracts run for months or years, and the accounts have to follow them. These are the issues that come up most in the sector.
Revenue across long contracts
Income has to be recognised as the work progresses, not only when invoices go out, and estimates change during the project.
Costs spread over many sites
Materials, labour and equipment move between projects, so the cost of each contract is hard to see.
Retentions and late payments
Clients hold back retentions and pay late, which ties up cash and makes receivables hard to judge.
Foreign subcontractors
Payments to subcontractors and consultants outside Qatar can bring withholding tax that must be handled each month.
Audited accounts for tenders
Clients, banks and tender committees ask for audited financial statements, often at short notice.
Variations and claims
Change orders and claims are agreed late, so the figures in the accounts depend on judgement.
How we help a construction or contracting company
Most contractors need the same few services. Start with whichever is most urgent.
- 1Accounting and bookkeepingBooks kept every month with costs coded to each contract.View service
- 2External auditThe yearly audit, including the judgements on contract revenue.View service
- 3Corporate income tax returnThe yearly corporate income tax return on Dhareeba.View service
- 4Withholding taxWithholding tax on payments to subcontractors and consultants abroad.View service
- 5Special purpose auditReports on a single project or contract when a client or lender asks.View service
- 6Budgeting and forecastingCash forecasts that follow the payment terms of each project.View service
We agree each engagement separately. If we keep your books or prepare your accounts, a different firm must audit them. Audit work also depends on the registrations required for your company.
Why contract accounts need care
A contractor earns its income as the work moves forward, so the accounts follow the progress of each contract. That means estimates of total cost, the stage the work has reached, and how variations and claims are treated.
Small changes in those estimates move the profit for the year. We set up the records so each contract can be followed from tender to final account, and the figures stand up when the auditor or a client looks at them.
- A cost record for each contract
- Revenue that follows progress
- Retentions and claims tracked
- Accounts ready for the audit
How we work with a contractor
- 1
A short first call
You tell us about the company and its contracts. We tell you what applies.
- 2
Fixed fee in writing
A written proposal with what we do, what we need from you and the price.
- 3
Records by contract
Costs and income kept per project through the year.
- 4
Audit and return on time
Year-end accounts, the audit and the tax return, planned together.
Get expert advice for your business
Tell us what you need. We reply with a written proposal covering the scope, the documents we need and the timeline.
Questions construction companies ask us
Short answers. Open a question to read the answer.
Does a construction company in Qatar need an audit?
Often, yes. The General Tax Authority’s rules require audited accounts with the tax return above set limits on capital and income, and clients, banks and tender committees often ask for audited accounts too. For a contractor, the audit focuses on contract revenue, costs and retentions, so the records for each contract need to be kept up to date. Tell us about your company and we confirm what applies.
How is revenue on a construction contract recognised?
Under IFRS 15, revenue is recognised over time only when the contract meets one of the standard’s criteria, such as the customer controlling the asset as it is built. Otherwise, revenue is recognised when control transfers. For work recognised over time, a suitable progress measure may compare costs incurred with expected total costs. We review the contract before choosing the treatment.
How should retentions be recorded?
Retention is not automatically a receivable just because work has been billed. Under IFRS 15, it is a receivable when the right to payment is unconditional apart from time; if further performance conditions remain, it may be a contract asset. Track retentions by contract, release conditions and expected payment date, and assess recoverability. We review the terms with you.
What happens when a contract is expected to make a loss?
The expected loss is recognised as soon as it is foreseen, not spread over the rest of the contract. Under IAS 37, a contract whose unavoidable costs are more than the benefits expected from it is onerous, and a provision is made for the loss. This depends on up-to-date cost-to-complete estimates, so we review them with you before the accounts are closed.
Can you report on a single project for a client or lender?
Yes. When a client, a lender or a partner asks for a report on one contract or project, we agree with them what the report must cover and what kind of report they need. We then carry out the work and report on that project only, separately from the yearly audit.
Tax answers checked against the General Tax Authority’s published texts on 13 October 2026. General Tax Authority
Other industries and companies we work with
Tell us what you need. We reply with a written proposal.
You get the scope, the papers we need and the time it takes.
- 1You send your details by WhatsApp or email.
- 2We read them and ask anything we need to know.
- 3You get a written proposal: scope, papers and timing.